Hybrid brokers and the C-book.
A hybrid broker sends some client trades to liquidity providers (A-book) and keeps others in house, taking the other side itself (B-book). Routing usually depends on account results, trade size, style and total exposure. C-book has no fixed definition; it most often means splitting one trade, hedging part and keeping the rest.
Ce contenu n'existe pour l'instant qu'en anglais.
A broker does not have to pick one way of handling every trade. It can pass some orders to a bank or other liquidity provider, keep others on its own books, and change the mix as conditions change.
That mix is called a hybrid model. The C-book is a looser label for some of the ways a broker splits or manages that risk, and people use it to mean different things.
What is a hybrid broker?
In the A-book and B-book lesson the two models looked separate. On the A-book, the broker passes your trade to a liquidity provider (LP) and earns from a spread markup or commission.
On the B-book, the broker keeps your trade and takes the other side itself. When you lose, it gains, and when you win, it pays.
A hybrid broker runs both books at the same time. Each order, or each client account, goes to one book or the other under rules the broker sets, usually applied automatically by its risk software.
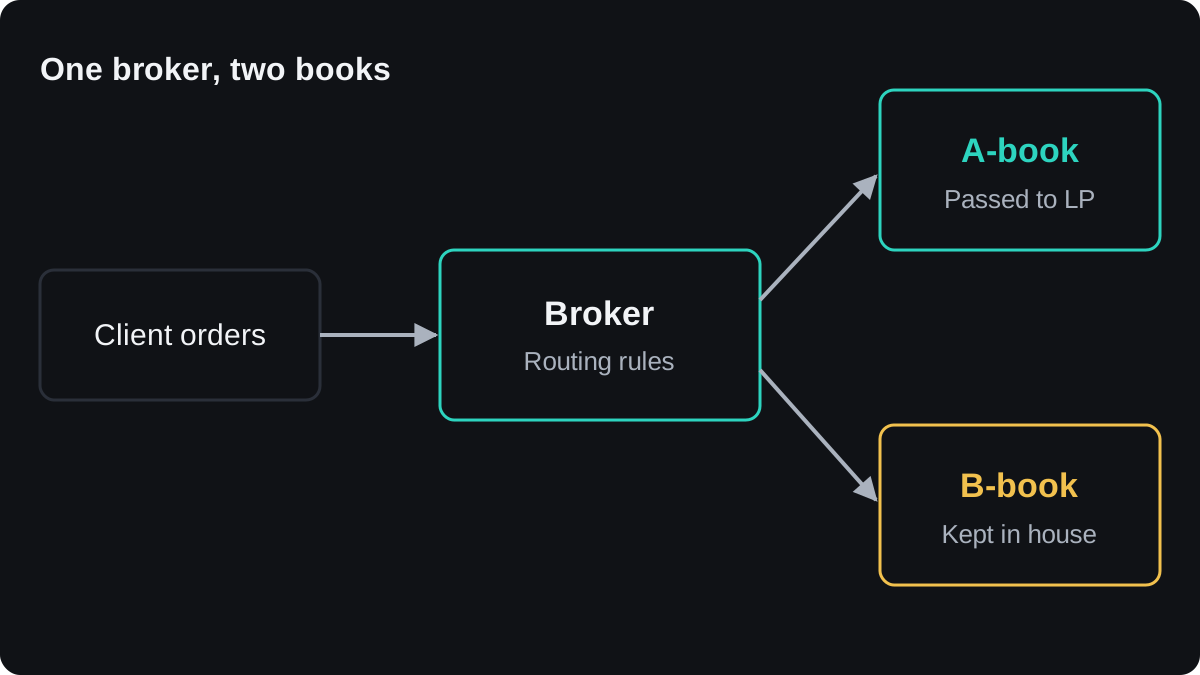
Pure models in either direction are uncommon among retail brokers, because each has a cost. A pure A-book broker gives up any profit from client losses, and a pure B-book broker carries the full risk of clients who win.
How does a hybrid broker choose a book for each trade?
Brokers do not publish their routing rules. What follows is the typical logic, and any one broker may weigh things differently.
- An account that wins steadily over many trades is costly to hold on the B-book, so it is more likely to be passed to an LP.
- A large order adds a lot of risk at once, so the broker may hedge it even if it keeps small orders in house.
- Very short trades that profit from tiny price delays, or trades opened around news releases, are hard to hold in house.
- A broker may hedge thin or volatile instruments and keep busy pairs, or do the reverse, depending on where it sees risk.
- If clients crowd onto one side of a pair, the broker's own position grows until it decides to hedge part of it.
The routing can change over time. A new account may start on the B-book and be moved to the A-book once its results show a pattern.
How does a hybrid broker hedge part of its exposure?
Routing single trades is one tool. The other is to hedge the broker's net position after it has matched buyers against sellers, as the internalisation lesson explained.
Here is a worked example with round illustrative numbers. One pip on one standard lot of EUR/USD is worth $10.
- Clients hold 30 lots long EUR/USD and 18 lots short.
- The broker matches 18 lots of buying against 18 lots of selling. Those cancel out, so it carries no price risk on them.
- That leaves 30 minus 18 = 12 lots of client buying. The broker is on the other side, so it is short 12 lots.
- Its policy allows at most 5 lots of open risk on this pair. It buys 12 minus 5 = 7 lots from an LP.
- The broker now keeps 5 lots of risk, so each pip moves its result by 5 × $10 = $50.
- If EUR/USD rises 20 pips, the broker loses 20 × $50 = $1,000 on the unhedged part.
- With no hedge at all, the loss on 12 lots would have been 12 × $10 × 20 = $2,400.
The 7 hedged lots net to zero: what the broker owes clients on them, it earns back from the LP.
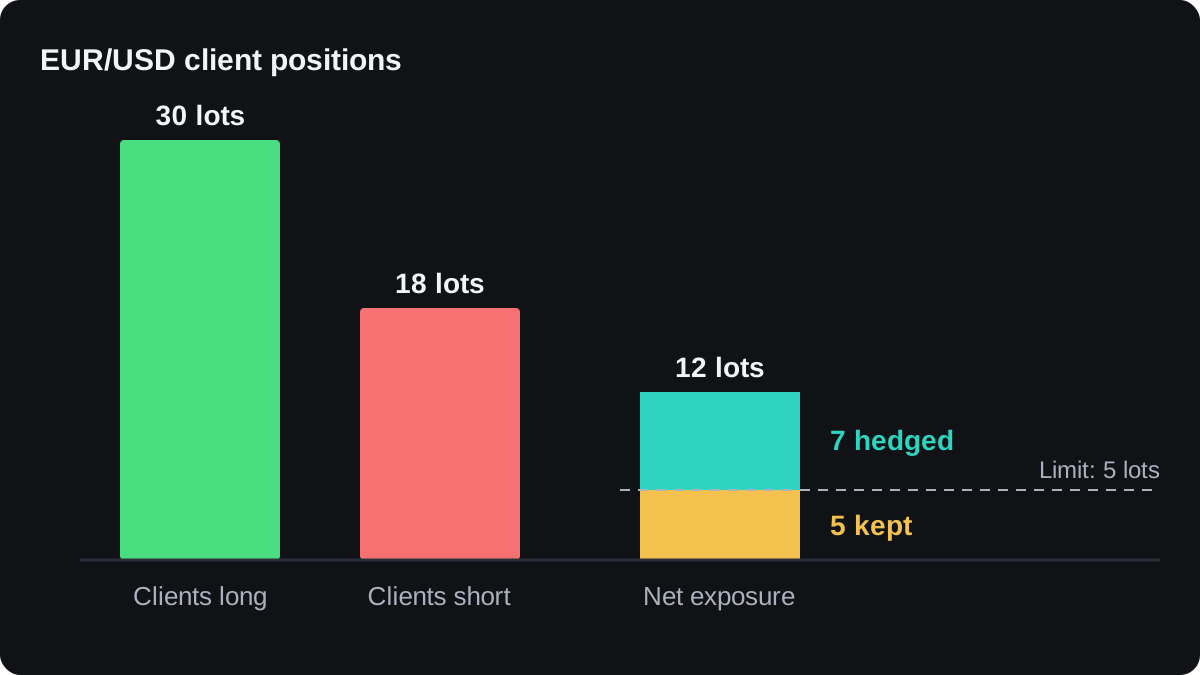
If EUR/USD falls 20 pips instead, the 5 kept lots earn the broker $1,000. That two-way bet is the B-book part of a hybrid, and spreads and commission come on top either way.
Real limits are set by each broker and can change during the day, so treat the 5 lot figure as an illustration.
What does C-book mean?
C-book is trade jargon with no official definition. Ask what someone means by it before you assume.
The most common use is partial hedging of each trade. The broker sends a fixed share of an order to an LP and keeps the rest on its own book.
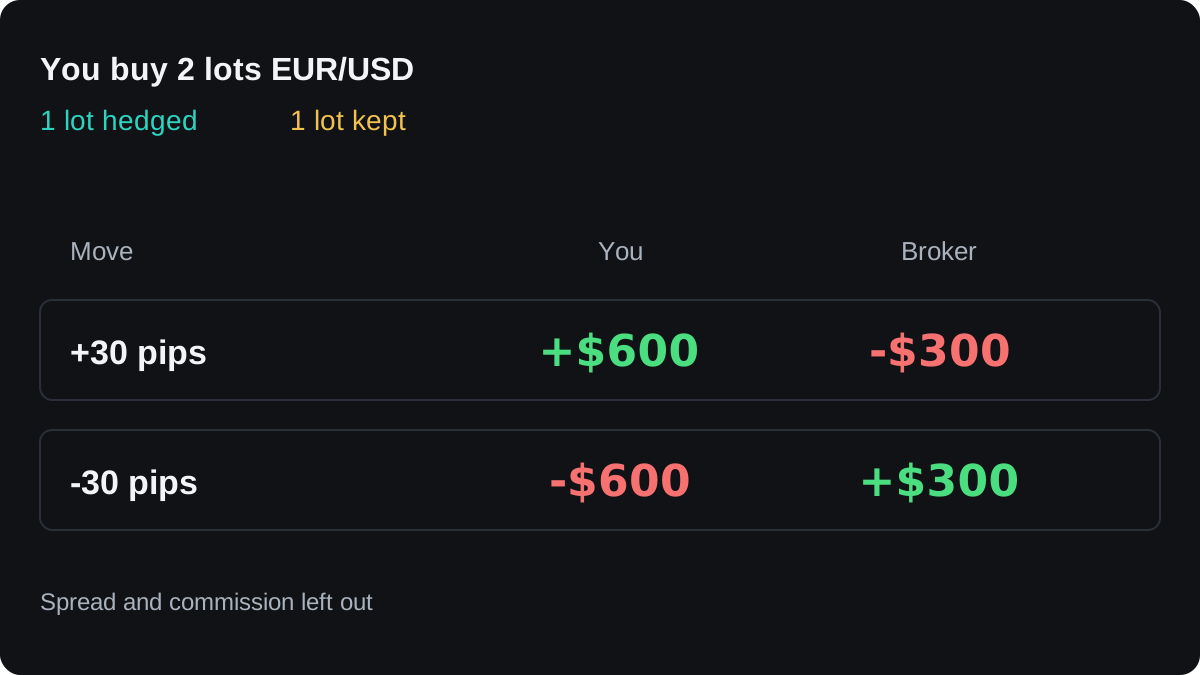
Say you buy 2 lots of EUR/USD and the broker's rule is to hedge 50%. It buys 1 lot from an LP and keeps the other lot. Each pip on your 2 lots is worth 2 × $10 = $20.
If EUR/USD rises 30 pips, you gain 30 × $20 = $600. The broker pays you that, earns 30 × $10 = $300 on its hedge, and ends $300 down.
If EUR/USD falls 30 pips, you lose $600. The broker collects it, loses $300 on its hedge, and ends $300 up.
In both cases the broker's result is half of yours with the sign reversed. Spread and commission are left out to keep the sums clear.
Some people use C-book for something else: a broker taking its own directional positions based on client flow. One example is trading in the same direction as accounts it has marked as consistently profitable, beyond simply hedging them.
Others use the word for any risk book run mostly by algorithms that adjust the hedged share in real time.
Whatever the label, your question stays the same, which is whether the broker gains when you lose. The counterparty lesson covers how to find out.
What a hybrid model means for your trades
A hybrid broker profits from some clients' losses and earns fees from others. That is a conflict of interest, and on its own it does not mean you get worse prices.
The risk lies in how the conflict is handled. A broker holding your trade could be tempted to widen spreads, slow fills or reject orders when you are winning.
Rules in many places require licensed brokers to manage conflicts of interest and to execute orders on fair terms. The detail and the enforcement differ by country, so a licence is a starting point.
You usually cannot see which book your trade sits on. You can still check a few things:
- Read the broker's order execution policy and conflicts of interest policy. Many brokers state there whether they act as principal, meaning they take the other side.
- Check the licence with the steps in the regulation lesson.
- Keep a record of your own fills. Slippage that only ever goes against you, or frequent requotes on winning trades, are worth noting. The execution quality lesson shows how to measure this.
An A-book route is no promise of good execution either. A broker can pass orders on and still add a wide markup or route them slowly, so judge it on the costs and fills you can measure.
A broker's hedging policy, when it publishes one, sets out how far it offsets the risk it takes from clients.
Questions fréquentes
Is a hybrid broker bad for traders?
Not necessarily. It has a conflict of interest on the trades it keeps, so judge it by its licence, its published policies and the costs and fills you actually get.
Can I ask my broker whether I am on the A-book or B-book?
You can ask, but brokers generally do not have to tell you account by account, and many will not. The execution policy and conflicts of interest policy are more reliable written sources.
What is the difference between a C-book and a hybrid broker?
A hybrid broker uses both the A-book and the B-book. C-book is a looser term, most often meaning a trade that is partly hedged and partly kept, though some use it for directional trading based on client flow.
Do brokers move profitable traders to the A-book?
Hybrid setups are often built to allow this, because a steady winner costs a broker money on the B-book. Whether and when it happens depends on each broker's private rules.
Continuer à apprendre
 Chapitre 1How to choose a forex broker.To choose a forex broker, check four things before you deposit. Confirm the licence on the regulator's own register, work out the full cost of a trade from spread, commission and swap, test how orders are filled, and make a small withdrawal to see how payouts work. A broker that fails the licence check needs no further study.
 Chapitre 1What does a forex broker actually do?A forex broker opens your trading account, streams buy and sell prices, accepts your orders and fills them, either with outside liquidity providers or by taking the other side itself. It also holds your deposit, sets aside margin while trades are open, applies leverage, charges or pays swap and closes positions at stop out.
 Chapitre 1Is your forex broker regulated? How to check a licence.A regulated forex broker holds a licence from a government authority such as the UK's FCA or Australia's ASIC. To check it, find the legal company name and licence number on the broker's site, then search them on the regulator's own register and confirm the website and contact details match.
 Chapitre 1Red flags of a fake or unsafe forex broker.A fake or unsafe forex broker usually shows itself in a few ways: no licence or a cloned one, promises of guaranteed profit, pressure to deposit, payments to personal or unrelated accounts, bonus terms that lock your money, and withdrawals that stall or need a fee paid first. Check the regulator's register and test a small withdrawal.
 Chapitre 1Who is on the other side of your forex trade?In retail forex, the other side of your trade is usually your broker. Spot forex has no central exchange, so deals are made over the counter, and your trade is most often a cash-settled CFD with the broker. The broker may keep that risk, hedge it with a liquidity provider, or match it against other clients.
 Chapitre 1How forex brokers make money.Forex brokers earn from the spread, the gap between the buy and sell price, often widened by a markup they keep. Many also charge commission per lot and add a margin to overnight swap. A broker that takes the other side of your trade can also profit when you lose.
 Chapitre 1A-book and B-book brokers explained.An A-book broker passes your trade to an outside liquidity provider and earns from a markup or commission, so your win or loss does not change its income. A B-book broker takes the other side itself, so it gains when you lose and pays when you win. Many brokers use both.
 Chapitre 1How A-book brokers earn, and what limits them.A pure A-book broker passes each client trade to a liquidity provider, so it earns nothing from your losses. Its income is a markup on the spread, a commission per lot, swap markups and fees. Income per lot is small after routing costs, so the broker needs high volume, and it can only offer the prices its providers quote.
 Chapitre 1STP and ECN execution explained.STP, straight-through processing, means your broker passes your order automatically to outside liquidity providers and usually earns by widening the spread. ECN, electronic communication network, means your order meets prices from many participants in a shared order book, usually with a raw spread plus a commission. Both are labels, so check how your broker actually routes orders.
 Chapitre 1Internalisation: how brokers net client orders.Internalisation is when a broker offsets client buy orders against client sell orders inside its own books. Opposite trades cancel, so only the leftover net position is left to hedge or keep. This cuts the broker's outside costs and risk, while each client's contract stays with the broker, who remains the counterparty.
 Chapitre 1Your broker's hedging policy and why it matters.A broker's hedging policy decides whether you can hold a buy and a sell on the same pair in one account, and how much margin that pair uses. Hedging accounts keep both positions open; netting accounts close or shrink the first one. Margin on a hedged pair can be full, one leg or zero.
 Chapitre 1Where your broker's prices come from.Your broker's prices start as quotes streamed by liquidity providers, mostly banks and non-bank trading firms. An aggregator keeps the highest bid and lowest ask from these streams, and the broker usually adds a markup before the price reaches your platform. Different providers, markups and timing mean two brokers can show different prices at the same moment.
 Chapitre 1How to judge a broker's order execution.Good order execution means your trades fill quickly, close to the price you asked for, with few requotes or rejections. To judge it, log the requested and filled price of every market order over dozens of trades. Slippage should run in both directions, with some fills better than requested, and news-time orders kept separate.
Courtiers partenaires

