Where your broker's prices come from.
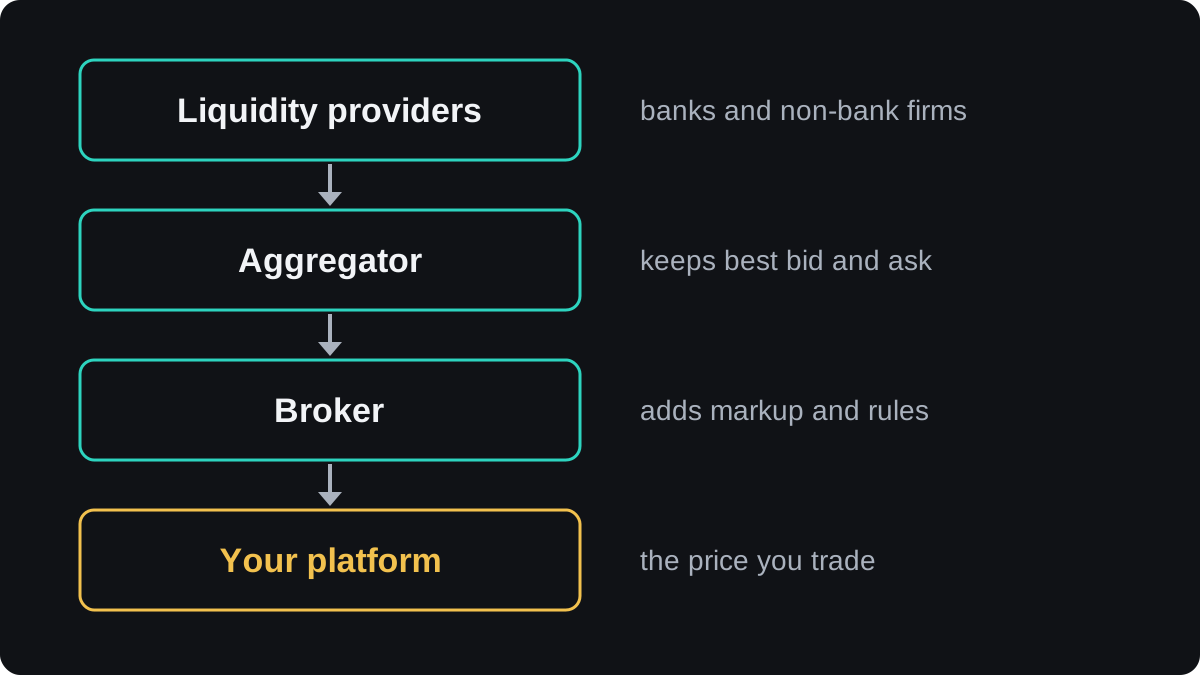
Your broker's prices start as quotes streamed by liquidity providers, mostly banks and non-bank trading firms. An aggregator keeps the highest bid and lowest ask from these streams, and the broker usually adds a markup before the price reaches your platform. Different providers, markups and timing mean two brokers can show different prices at the same moment.
Konten ini baru tersedia dalam bahasa Inggris.
Open two trading platforms side by side and watch EUR/USD. At the same second, one might show a bid of 1.10001 and the other 1.10004.
Neither platform is broken. The forex market has no central exchange and no single official price, so each broker builds its own quote from the sources it buys from.
Who supplies the prices a broker shows?
The raw prices come from liquidity providers, firms that stream buy and sell prices to the broker many times a second and stand ready to trade at them. Most are large banks or electronic non-bank trading firms.
Each quote in that stream has a bid, an ask and a size, such as 1 million euros. The size is how much the provider will trade at that price before moving to a worse one.
Smaller brokers often cannot open accounts with large banks directly. Many reach them through a prime of prime, a firm that has a bank prime brokerage account and passes access, credit and prices on to smaller clients.
The quotes then pass through software that combines them, then through the broker's own pricing rules, and finally onto your screen. The glossary entry on the liquidity provider covers the term in brief.
How does a broker combine quotes from several providers?
The software that merges the streams is an aggregator. For each instrument it watches every incoming quote and keeps the highest bid and the lowest ask, because those are the best prices on each side.
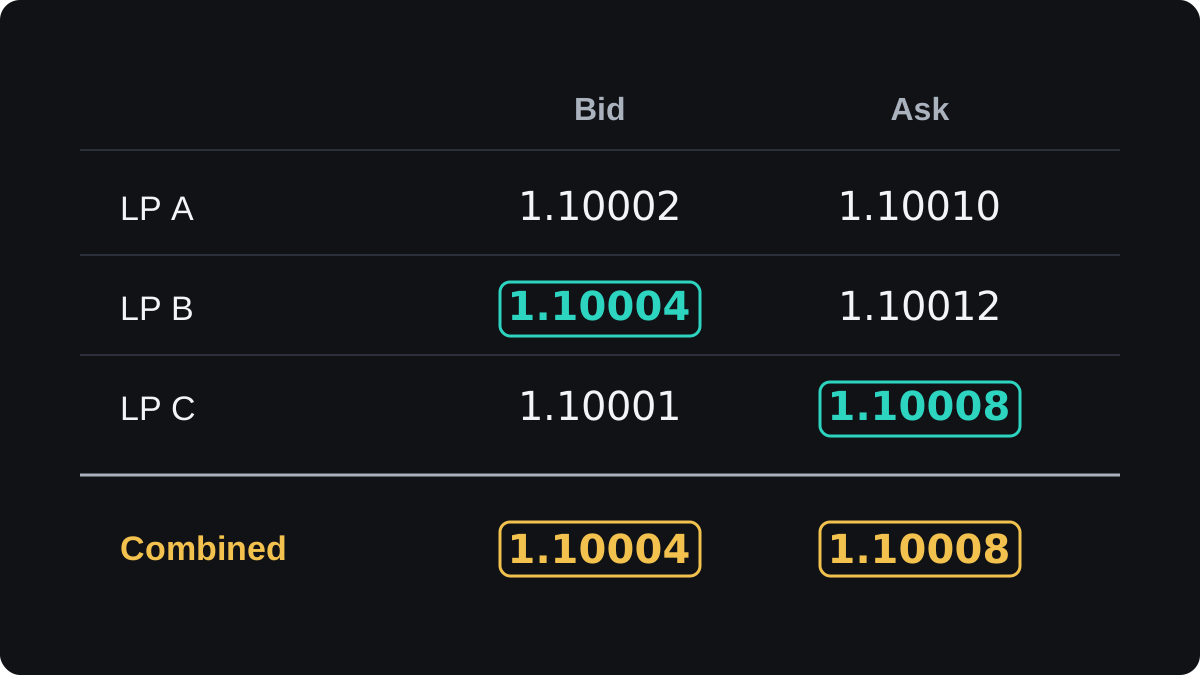
Here is an illustrative snapshot of EUR/USD from three providers at the same instant:
| Provider | Bid | Ask | Spread |
|---|---|---|---|
| LP A | 1.10002 | 1.10010 | 0.8 pip |
| LP B | 1.10004 | 1.10012 | 0.8 pip |
| LP C | 1.10001 | 1.10008 | 0.7 pip |
- The highest bid is 1.10004, from LP B.
- The lowest ask is 1.10008, from LP C.
- The combined quote is 1.10004 bid, 1.10008 ask.
- Its spread is 1.10008 minus 1.10004 = 0.00004, which is 0.4 pip.
The combined spread of 0.4 pip is tighter than any single provider's. This is one reason a broker connects to more than one source.
The best price only covers the size quoted with it. Say LP C offers 1 million euros at 1.10008 and an order needs 2 million.
The second million may fill at the next best ask, LP A's 1.10010. The average price is then 1.10009, half a pip worse than the screen showed. Retail orders are usually far smaller than these sizes.
What does the broker change before you see the price?
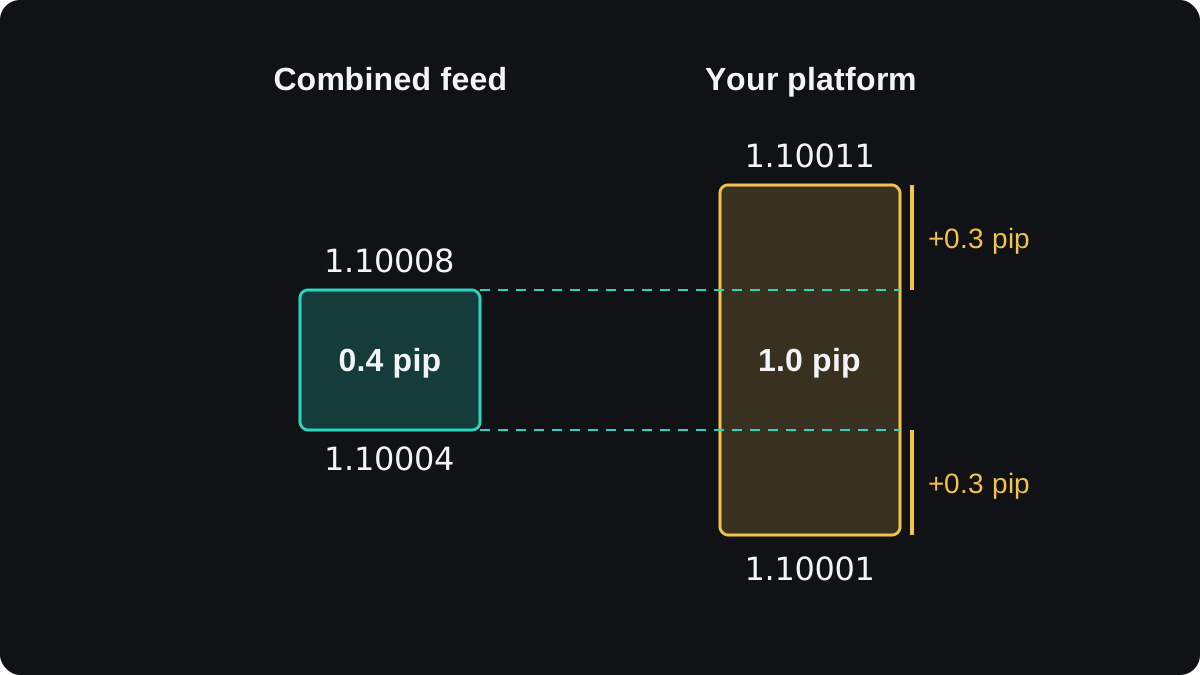
The combined quote is rarely what reaches your screen. Most brokers add a markup, a small amount pushed onto each side of the price, and the wider spread that results is part of how they are paid.
Continuing the example with an illustrative markup of 0.3 pip on each side:
- Bid: 1.10004 minus 0.00003 = 1.10001.
- Ask: 1.10008 plus 0.00003 = 1.10011.
- Your spread: 1.10011 minus 1.10001 = 0.00010, which is 1.0 pip.
- On one standard lot of EUR/USD a pip is worth $10, so the spread costs $10.
- Of that, 0.4 pip ($4) is the market spread and 0.6 pip ($6) is the markup.
On a raw spread account, the broker usually passes the combined quote through with little or no markup and charges a commission per lot instead. The lesson on Standard vs Raw accounts compares the two.
Pricing rules can also drop quotes that look stale or far from the rest, set a minimum spread, or widen the spread at certain times of day. These rules differ from broker to broker.
A broker that keeps some client trades in-house, as described in A-book and B-book brokers explained, usually still starts from market feeds. Prices that drift away from the wider market invite arbitrage against the broker.
Why do two brokers quote different prices at the same moment?
Every step above is a choice the broker makes, so two brokers rarely end up with identical numbers. The usual causes are:
- Different liquidity providers, so the best bid and ask each one receives differ.
- Different markups, which can also vary by account type at the same broker.
- Timing, because a feed that arrives a few milliseconds later can show a price the market has already left.
- Different filters and spread rules inside the pricing software.
Here is an illustrative pair of quotes taken at the same second:
| Broker | Bid (you sell) | Ask (you buy) | Spread |
|---|---|---|---|
| Broker X | 1.10001 | 1.10011 | 1.0 pip |
| Broker Y | 1.10004 | 1.10013 | 0.9 pip |
Broker Y has the tighter spread. At this second it also pays a seller 0.3 pip more, while Broker X charges a buyer 0.2 pip less. On one standard lot, those gaps are worth $3 and $2.
So the better entry price depends on which way you trade. A full round trip at one broker still costs that broker's spread, and quotes keep moving, so the average spread over many readings tells you more than one snapshot.
When do broker prices widen or jump?
A broker can only pass on what its providers are willing to quote. When providers turn cautious, they widen their spreads, cut the sizes they offer or pause, and every broker that relies on them shows the effect.
This tends to happen around major economic releases and when markets reopen after the weekend. It also happens at the daily rollover near 17:00 New York time, when spreads often widen for a short period.
Some providers also use last look, a short window after your broker sends an order in which the provider can still accept or reject it at the quoted price.
A rejection can reach you as a requote or a fill at a different price, which the slippage lesson explains.
How can you check your broker's prices?
Most brokers do not publish their provider list, but you can test the result yourself:
- Compare bid and ask on two brokers' platforms at the same moment, on several pairs and at several times of day.
- Watch the spread during a news release and at rollover as well as in quiet hours.
- Read the broker's order execution policy for how it sources prices and whether it adds a markup.
- Check published spread data, such as the spread comparison, and note when it was measured.
How your orders are filled against these prices is the subject of the next lesson, how to judge a broker's order execution.
Pertanyaan
Why is my broker's price different from a chart on another website?
Websites and other brokers use their own feeds, and some show only the bid, a mid price or a delayed quote. Gaps of a fraction of a pip are normal in a market with no single official price.
Do forex brokers make up their own prices?
A legitimate broker builds its quotes from market feeds, then applies its own markup and rules. Prices that sit far from other brokers for long periods are a warning sign worth checking.
What is a liquidity provider?
A firm, usually a bank or a non-bank trading firm, that streams buy and sell prices to a broker and stands ready to trade at them.
Why does the spread widen late in the New York day?
Around the daily rollover near 17:00 New York time, many providers widen or pause their quotes, so the combined spread a broker can offer widens too. It usually narrows again once normal quoting resumes.
Is a broker with more liquidity providers always better?
More sources can tighten the combined spread, but your final price also depends on the markup, the filters and how orders are filled. Compare the prices and fills you actually get.
Lanjut belajar
 Bab 1How to choose a forex broker.To choose a forex broker, check four things before you deposit. Confirm the licence on the regulator's own register, work out the full cost of a trade from spread, commission and swap, test how orders are filled, and make a small withdrawal to see how payouts work. A broker that fails the licence check needs no further study.
 Bab 1What does a forex broker actually do?A forex broker opens your trading account, streams buy and sell prices, accepts your orders and fills them, either with outside liquidity providers or by taking the other side itself. It also holds your deposit, sets aside margin while trades are open, applies leverage, charges or pays swap and closes positions at stop out.
 Bab 1Is your forex broker regulated? How to check a licence.A regulated forex broker holds a licence from a government authority such as the UK's FCA or Australia's ASIC. To check it, find the legal company name and licence number on the broker's site, then search them on the regulator's own register and confirm the website and contact details match.
 Bab 1Red flags of a fake or unsafe forex broker.A fake or unsafe forex broker usually shows itself in a few ways: no licence or a cloned one, promises of guaranteed profit, pressure to deposit, payments to personal or unrelated accounts, bonus terms that lock your money, and withdrawals that stall or need a fee paid first. Check the regulator's register and test a small withdrawal.
 Bab 1Who is on the other side of your forex trade?In retail forex, the other side of your trade is usually your broker. Spot forex has no central exchange, so deals are made over the counter, and your trade is most often a cash-settled CFD with the broker. The broker may keep that risk, hedge it with a liquidity provider, or match it against other clients.
 Bab 1How forex brokers make money.Forex brokers earn from the spread, the gap between the buy and sell price, often widened by a markup they keep. Many also charge commission per lot and add a margin to overnight swap. A broker that takes the other side of your trade can also profit when you lose.
 Bab 1A-book and B-book brokers explained.An A-book broker passes your trade to an outside liquidity provider and earns from a markup or commission, so your win or loss does not change its income. A B-book broker takes the other side itself, so it gains when you lose and pays when you win. Many brokers use both.
 Bab 1How A-book brokers earn, and what limits them.A pure A-book broker passes each client trade to a liquidity provider, so it earns nothing from your losses. Its income is a markup on the spread, a commission per lot, swap markups and fees. Income per lot is small after routing costs, so the broker needs high volume, and it can only offer the prices its providers quote.
 Bab 1STP and ECN execution explained.STP, straight-through processing, means your broker passes your order automatically to outside liquidity providers and usually earns by widening the spread. ECN, electronic communication network, means your order meets prices from many participants in a shared order book, usually with a raw spread plus a commission. Both are labels, so check how your broker actually routes orders.
 Bab 1Internalisation: how brokers net client orders.Internalisation is when a broker offsets client buy orders against client sell orders inside its own books. Opposite trades cancel, so only the leftover net position is left to hedge or keep. This cuts the broker's outside costs and risk, while each client's contract stays with the broker, who remains the counterparty.
 Bab 1Hybrid brokers and the C-book.A hybrid broker sends some client trades to liquidity providers (A-book) and keeps others in house, taking the other side itself (B-book). Routing usually depends on account results, trade size, style and total exposure. C-book has no fixed definition; it most often means splitting one trade, hedging part and keeping the rest.
 Bab 1Your broker's hedging policy and why it matters.A broker's hedging policy decides whether you can hold a buy and a sell on the same pair in one account, and how much margin that pair uses. Hedging accounts keep both positions open; netting accounts close or shrink the first one. Margin on a hedged pair can be full, one leg or zero.
 Bab 1How to judge a broker's order execution.Good order execution means your trades fill quickly, close to the price you asked for, with few requotes or rejections. To judge it, log the requested and filled price of every market order over dozens of trades. Slippage should run in both directions, with some fills better than requested, and news-time orders kept separate.

