Currency intervention.
Currency intervention is when a government or its central bank buys or sells currency in the market to push its exchange rate. Buying its own currency with foreign reserves props it up, and selling its own currency weakens it. For traders it means sudden large moves, and stops that can fill far from their price.
Konten ini baru tersedia dalam bahasa Inggris.
Exchange rates usually move because private buyers and sellers, such as banks and companies, trade with each other. Sometimes a government steps in as a buyer or seller itself, and the price can travel a long way in minutes.
Like geopolitical shocks, intervention does not arrive on a published schedule.
What does currency intervention look like?
Picture the yen falling week after week against the US dollar. Japan's Ministry of Finance decides the slide has gone too far. The Bank of Japan, acting on its instructions, sells US dollars from the country's savings and buys yen.
That is currency intervention: an official body buying or selling currency in the market to move its exchange rate. In most countries the central bank does the trading, sometimes on orders from the finance ministry, as in Japan.
The savings it spends are foreign reserves, the foreign currency and foreign government bonds held by a country's central bank or government.
The usual tool of a central bank is its interest rate, covered in the central banks lesson. Intervention is the direct route: placing orders in the market itself.
Which way can a country push its currency?
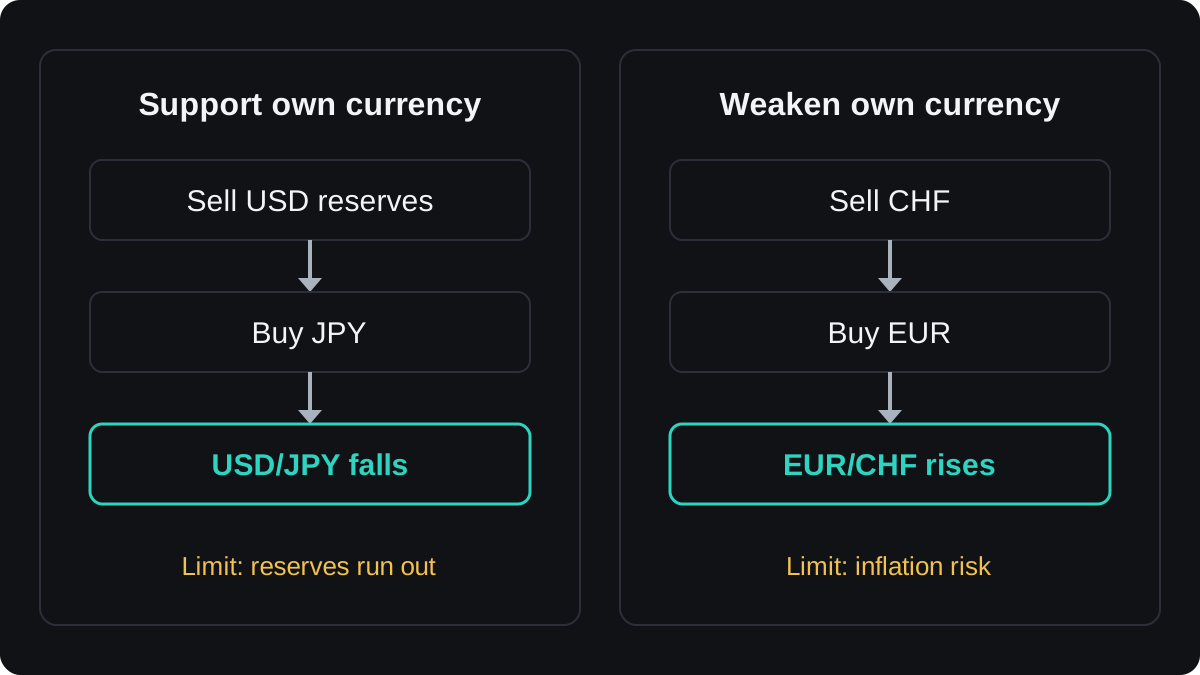
To support its currency, a central bank sells foreign reserves and buys its own currency. The extra demand lifts the price. In the yen example, buying yen pushes USD/JPY down.
To weaken its currency, it does the reverse and sells its own currency to buy foreign currency. The Swiss National Bank has done this to hold back the franc, which pushes EUR/CHF up.
The two directions have different limits. Support stops when reserves run low, because a country can only spend the foreign currency it holds.
Weakening has no such ceiling, since a central bank can create its own currency. The cost is that the new money can add to inflation at home.
Round illustrative numbers show the first limit. A country holds $100 billion in reserves, and defending its currency costs $5 billion a day. At that pace, 100 ÷ 5 = 20 trading days of defence remain.
Traders can do that sum too. If they expect the reserves to run out, they may keep selling, and the daily cost of defence rises.
Each trade also changes the amount of money in the home banking system. Buying yen with dollars takes yen out of circulation, which works like a small tightening of policy.
A central bank can cancel that side effect by buying or selling domestic bonds to put the same amount of money back, or take it out. This is sterilised intervention: the currency trade stays, and the money supply is left roughly where it was.
Why does intervention often fade?
Intervention changes supply and demand while the official orders are in the market. On its own, it leaves untouched the reasons money was flowing the other way, such as a wide gap in interest rates.
If a currency is falling because its rates sit far below other countries' rates, the pressure can return once the official buying stops. Economists still argue over how long sterilised intervention lasts, and the evidence is mixed.
Intervention is more likely to stick when a change in policy backs it up, or when several countries act together. Joint action of that kind is called coordinated intervention.
A well-known coordinated case is the Plaza Accord of 1985, when five large economies agreed to push the US dollar lower.
What happens when a peg or floor breaks?
Some countries intervene all the time to hold a fixed level. A peg ties a currency to another one at a set rate or inside a band. The Hong Kong dollar, for example, is held between 7.75 and 7.85 per US dollar.
A peg lasts only while the authorities are willing and able to defend it. When they stop, the price can jump to a new level with very little trading in between.
Switzerland gave a clear example with a floor, a level the price is not allowed to fall below. From 2011 the Swiss National Bank kept EUR/CHF at or above 1.20, so the franc could not strengthen past that rate.
When it dropped that floor in January 2015, EUR/CHF fell sharply within minutes. Stop orders in that move were filled far beyond their set prices.
Whether a country can defend its currency depends partly on its finances and politics, the subject of country risk.
How do traders spot the risk building?
Interventions are not listed on the economic calendar. The warning signs come from what officials say and from the price itself.
The first sign is a fast, one-way move. Japanese officials, for example, have often said that rapid moves are undesirable, so a sharp slide over a few days raises the risk.
The next is verbal intervention, sometimes called jawboning. Officials describe the moves as excessive or say they are ready to act. Words cost nothing, and they can slow a move on their own.
A stronger signal is a rate check, when the central bank calls dealing banks and asks for a quote. Markets read it as a sign that real orders may follow, though news of a rate check usually arrives second hand.
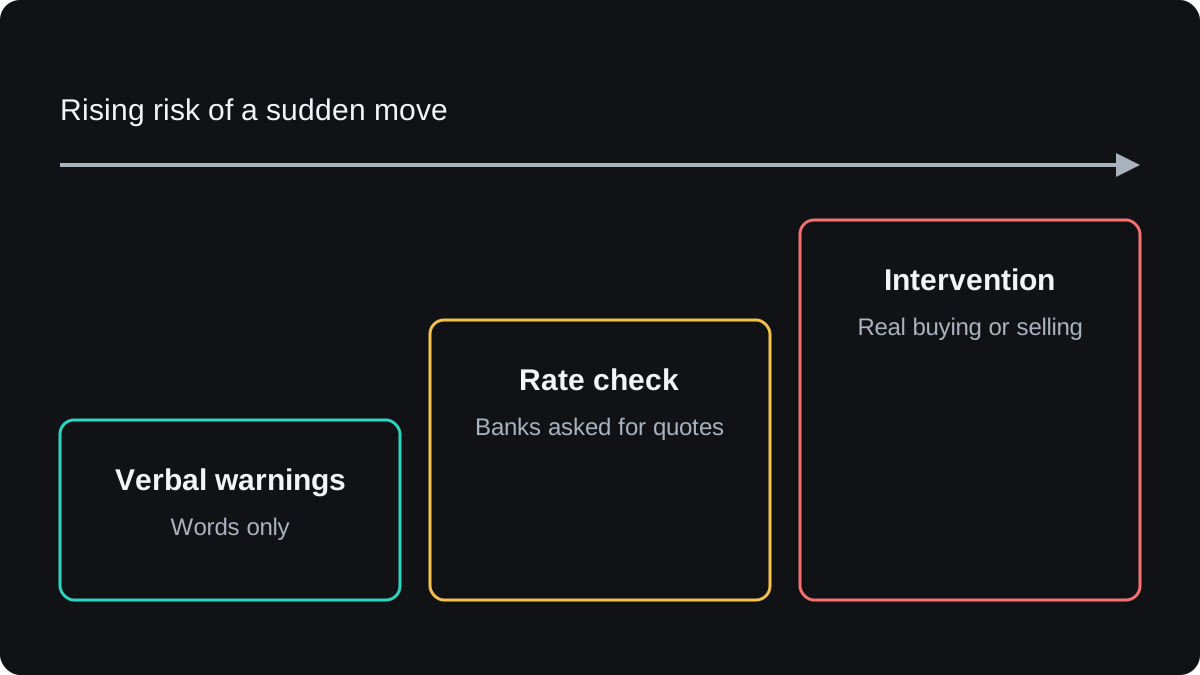
The steps do not always come in this order. An intervention can arrive with no warning, and some countries confirm it only later, if at all. Japan's Ministry of Finance publishes its intervention totals after the event.
What can intervention do to an open trade?
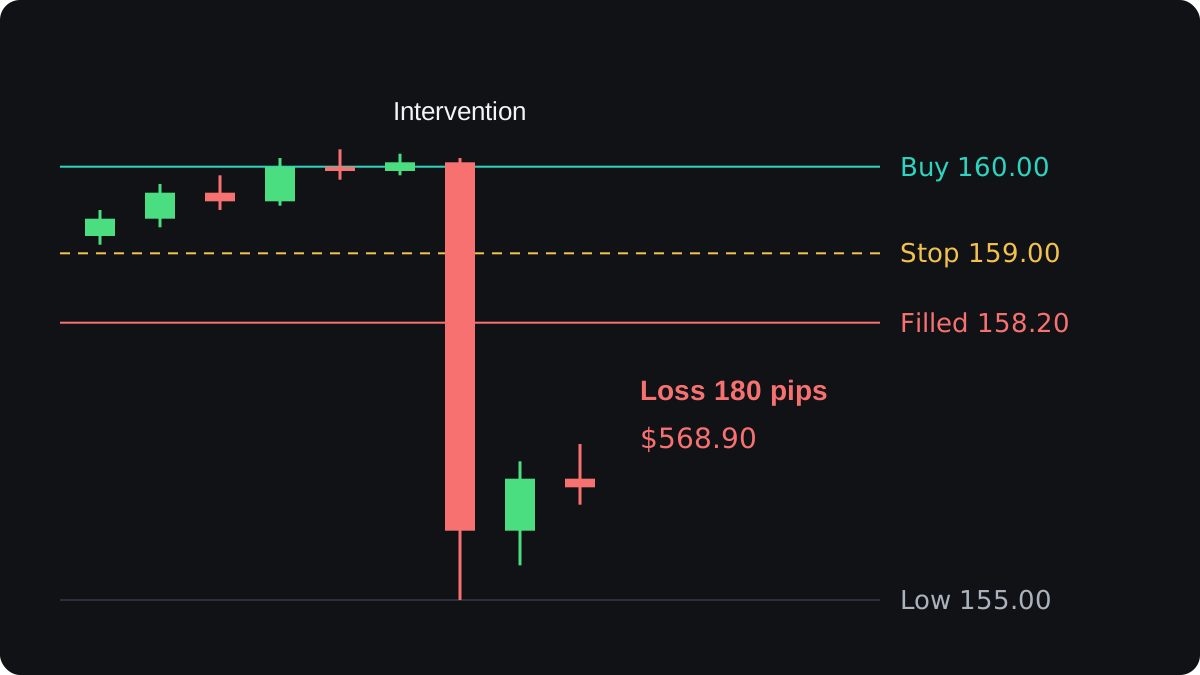
Say you buy 0.50 lot of USD/JPY at 160.00, with a stop loss at 159.00. All prices here are illustrative, and the spread is left out to keep the sums clear.
- Work out the pip value. On a JPY pair a pip is 0.01, and 0.50 lot is 50,000 dollars, so one pip is 50,000 × 0.01 = ¥500.
- Work out the planned risk. 160.00 minus 159.00 = 1.00, which is 100 pips. 100 × ¥500 = ¥50,000, or $314.47 at 159.00.
- The intervention hits. USD/JPY drops from 160.05 to 155.00 within one candle. Your stop turns into a market order at 159.00, and the next available price is 158.20.
- Work out the real loss. 160.00 minus 158.20 = 1.80, which is 180 pips. 180 × ¥500 = ¥90,000, or $568.90 at 158.20.
- With no stop at all, at the low of 155.00 the loss is 500 pips. 500 × ¥500 = ¥250,000, or $1,612.90 at 155.00.
| Outcome | Pips | Yen | USD (illustrative) |
|---|---|---|---|
| Planned stop at 159.00 | 100 | ¥50,000 | $314.47 |
| Stop filled at 158.20 | 180 | ¥90,000 | $568.90 |
| No stop, low of 155.00 | 500 | ¥250,000 | $1,612.90 |
The 80 pip gap between the stop price and the fill is slippage. The stop still cut the loss well short of the low, though it could not deliver its exact price.
Spreads can also widen sharply in those minutes, which adds to the cost of any order filled then.
One way to plan for this is a smaller size on a pair near a level officials have warned about. At 0.25 lot a pip is worth ¥250, so the same 180 pips would cost ¥45,000, half as much.
The pip value calculator shows what each pip is worth at any size and account currency.
Pertanyaan
Why would a country want a weaker currency?
A weaker currency makes a country's exports cheaper abroad and can lift prices at home when inflation is too low. A currency that rises fast can hurt exporters, which is why some central banks lean against it.
How can I tell if a central bank has intervened?
Look for a sudden large move with no data release behind it, then check official statements and news reports. Some authorities confirm at once, some only later, and some never.
Does intervention change the trend?
Sometimes, for a while. If the forces behind the trend, such as an interest rate gap, stay the same, the move can resume once the official buying or selling stops.
Can a stop loss protect me during an intervention?
It limits the loss, but in a fast move it can fill well past its price. Sizing the trade so a slipped stop is still an acceptable loss is one way to plan for that.
What is the difference between verbal and actual intervention?
Verbal intervention is officials warning that they may act. Actual intervention is the central bank placing real buy or sell orders in the market.
Lanjut belajar
 Bab 3Geopolitical risk and forex.Geopolitical risk is the chance that elections, conflicts or sanctions change a country's economy or its links with the world. Currencies reprice when that risk shifts, often in sudden jumps. Money tends to leave risk-sensitive currencies such as the Australian dollar and move into safe havens such as the US dollar, Japanese yen and Swiss franc.
 Bab 3Country risk and currency value.Country risk is the chance that a country's debts, deficits or politics make its assets less safe to hold. Large current account deficits, heavy debt owed in foreign currency, thin reserves and unstable politics tend to make investors demand higher interest rates or sell the currency. These forces work slowly and give little help with timing trades.

